Mortgage Calculator
This free mortgage calculator estimates your full monthly home payment: principal and interest plus property tax, home insurance, HOA fees and PMI. See how much of the loan goes to interest and how fast the balance falls each year.
Your result
What is a mortgage calculator?
A mortgage calculator estimates the monthly cost of buying a home with a loan. Unlike a basic loan calculator, it adds the costs that usually come with a mortgage payment: property tax, homeowners insurance, homeowners association (HOA) fees and private mortgage insurance (PMI). The result is a realistic figure you can compare with your monthly budget before you make an offer.
How to use this mortgage calculator
- Enter the home price and your down payment (as a percent or an amount).
- Enter the interest rate and loan term offered by your lender.
- Add yearly property tax and home insurance, plus any monthly HOA or maintenance fee.
- If your down payment is under 20%, set the PMI rate your lender quotes. The mortgage calculator adds PMI only when it applies.
- Open the yearly schedule to see how much principal and interest you pay each year.
Mortgage payment formula
The principal-and-interest part is a standard fixed-rate amortizing payment. Taxes, insurance, HOA and PMI are then added on top:
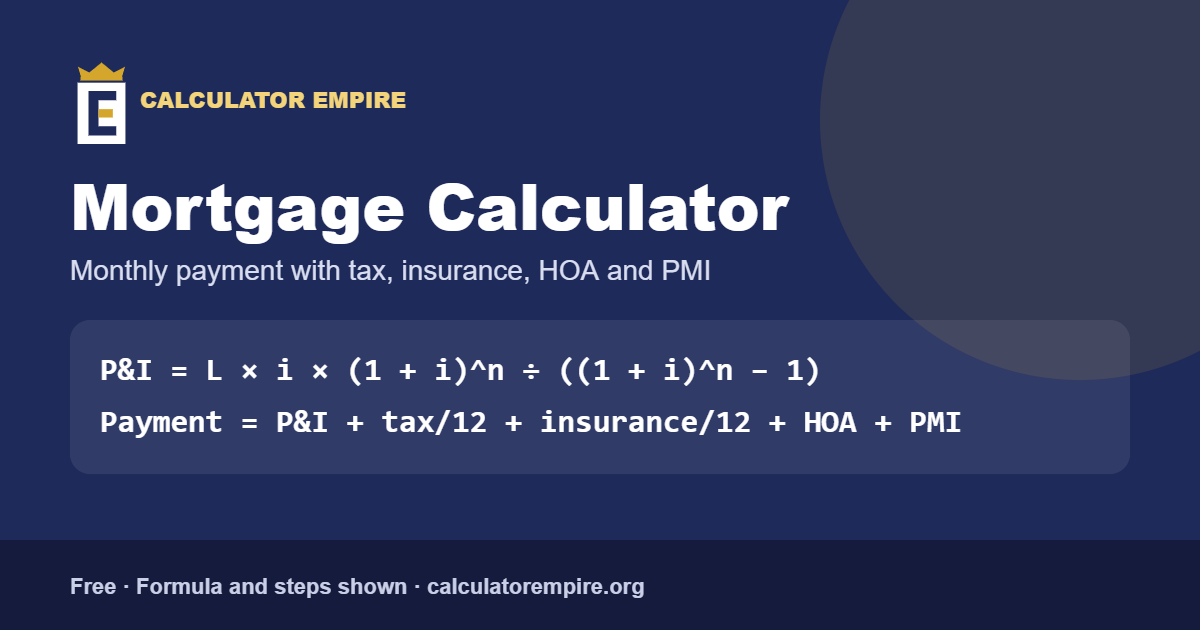
P&I = L × i × (1 + i)n ÷ ((1 + i)n − 1)
Monthly payment = P&I + tax ÷ 12 + insurance ÷ 12 + HOA + PMI
- L = loan amount = home price − down payment
- i = monthly rate = yearly rate ÷ 12 ÷ 100
- n = number of monthly payments = years × 12
- PMI = loan × PMI rate ÷ 12 (only when the down payment is below 20%)
Mortgage calculator worked example
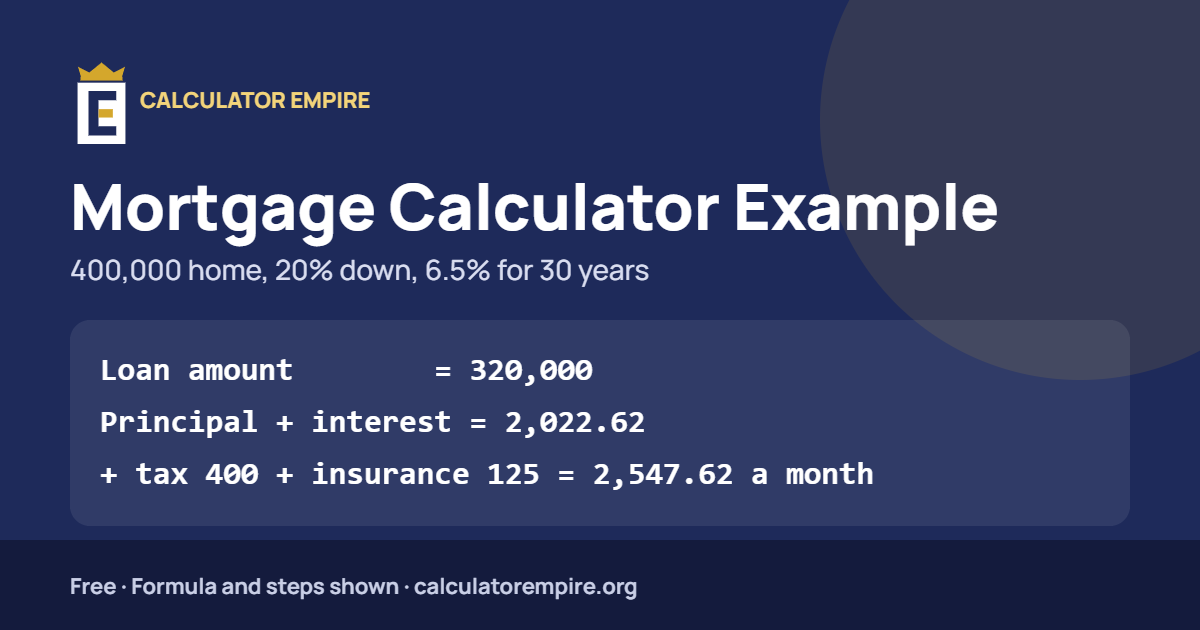
A 400,000 home with 20% down, a 6.5% rate for 30 years, 4,800 a year property tax and 1,500 a year insurance:
- Loan L = 400,000 − 80,000 = 320,000
- i = 6.5 ÷ 12 ÷ 100 ≈ 0.0054167; n = 360
- P&I ≈ 2,022.62 a month
- Tax 4,800 ÷ 12 = 400; insurance 1,500 ÷ 12 = 125; PMI = 0 because the down payment is 20%
- Total ≈ 2,547.62 a month. Over 30 years you pay about 408,142 in interest.
The same home with 10% down
With only 40,000 down, the loan is 360,000. Principal and interest rise to about 2,275.44, and PMI at 0.5% adds 150 a month, so the total becomes about 2,950.44 – roughly 403 more each month than with 20% down.
15-year vs 30-year mortgage
| Term | Monthly P&I | Total interest |
|---|---|---|
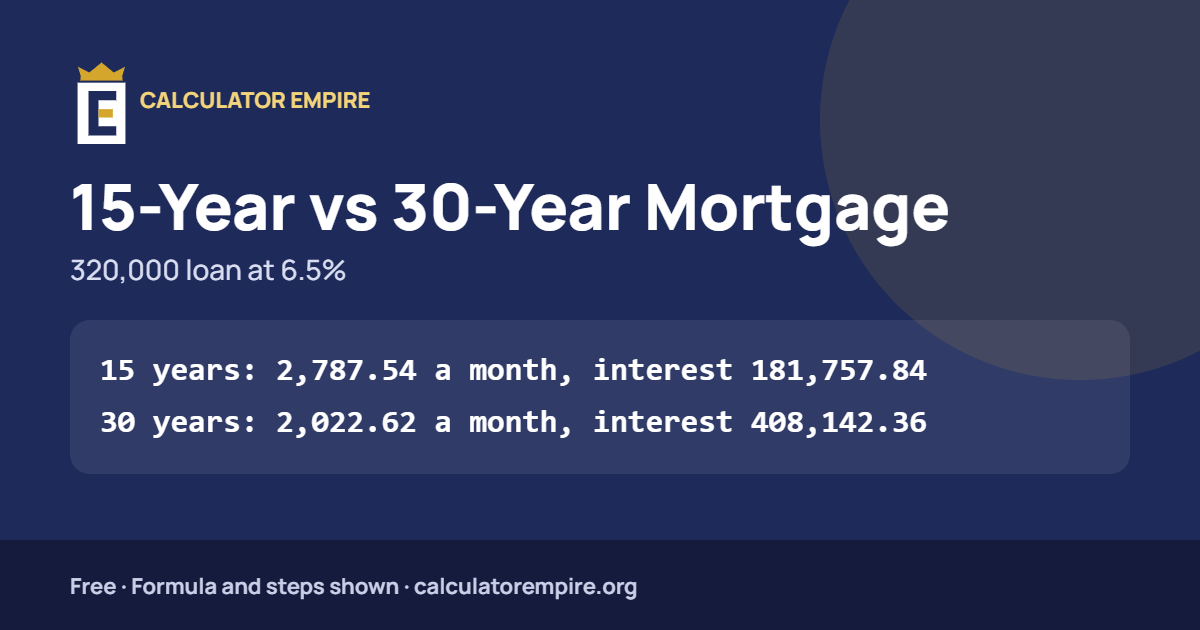
| 15 years | 2,787.54 | 181,757.84 |
| 30 years | 2,022.62 | 408,142.36 |
On a 320,000 loan at 6.5%, the 15-year mortgage costs about 765 more per month but saves more than 226,000 in interest. In practice, 15-year loans often have slightly lower rates too, which widens the gap.
What makes up a mortgage payment (PITI)
- Principal – the part that repays the loan balance.
- Interest – the lender’s charge for the money, highest in the early years.
- Taxes – property tax set by your local government, often collected monthly into escrow.
- Insurance – homeowners insurance, plus PMI when the down payment is below 20%.
How much house can I afford?
Many lenders use the 28/36 guideline: housing costs up to about 28% of gross monthly income, and all debt payments up to about 36%. If your household earns 9,000 a month before tax, that suggests a housing payment of roughly 2,520. Use the mortgage calculator to find the home price whose total payment stays under your limit, and remember to budget for maintenance and closing costs.
Ways to lower your mortgage payment
- Put down at least 20% to avoid PMI.
- Compare lenders: even a small rate cut lowers the payment for the whole term.
- Buy points to lower the rate if you plan to stay in the home for many years.
- A 15-year term has a higher monthly payment but far less total interest.
- Ask your local tax office whether you qualify for property tax exemptions.
Figures are estimates. Your lender’s Loan Estimate will include exact taxes, insurance, closing costs and any escrow requirements.
Frequently asked questions
What is included in a mortgage payment?
Usually principal and interest, plus property tax and homeowners insurance held in escrow (PITI). Many loans also include PMI, and some homes have HOA fees paid separately.
How is a mortgage payment calculated?
Principal and interest use the formula L × i × (1 + i)^n ÷ ((1 + i)^n − 1). The mortgage calculator then adds monthly property tax, insurance, HOA and PMI.
How much house can I afford?
A common rule is to keep housing costs under about 28% of gross monthly income and total debt under 36%. Enter different home prices in the calculator until the payment fits.
When can I stop paying PMI?
On most conventional loans you can ask to remove PMI once your balance falls to 80% of the home’s original value, and it ends automatically at 78%. Check your loan terms.
Is a 15-year or 30-year mortgage better?
A 15-year loan costs more each month but saves a large amount of interest. A 30-year loan keeps the payment lower and more flexible. The right choice depends on your budget.
How much should I put down on a house?
20% avoids PMI and lowers the payment, but many loans accept 3–10% down. A smaller down payment means a bigger loan, PMI and more interest.
Does the mortgage calculator include closing costs?
No. Closing costs are paid once at purchase, usually a few percent of the price. Budget for them separately.
What is an amortization schedule?
It is a table that shows how each payment is split between interest and principal and how the balance falls over time. Open the yearly schedule under the calculator to see it.
How does the interest rate affect my payment?
A higher rate raises both the monthly payment and total interest. On a 320,000 loan, each 1% increase adds roughly 200 or more to the monthly payment.
Does this work outside the US?
Yes. Choose your currency and enter local tax and insurance costs. Set PMI to 0 if your country does not use mortgage insurance.
Sources
Related calculators
- Loan Calculator
- Auto Loan Calculator
- Compound Interest Calculator
- Inflation Calculator
- Savings Goal Calculator
- All Finance Calculators
Spotted an error? Tell us and we will check it.