Loan Calculator (EMI Calculator)
Use this free loan calculator to find your monthly payment (EMI), the total interest you will pay and a year-by-year repayment schedule. It works for personal, home, car, education and business loans with a fixed interest rate.
Your result
What is a loan calculator?
A loan calculator is a tool that works out the fixed monthly payment needed to repay a loan, together with the total interest, from three numbers: the amount borrowed, the interest rate and the repayment period. In Pakistan and India the monthly payment is usually called the EMI (equated monthly instalment), so a loan calculator and an EMI calculator do the same job.
Knowing the payment before you apply helps you choose a loan you can afford, compare offers from different banks and decide whether a shorter or longer term suits your budget.
How to use this loan calculator
- Enter the loan amount you plan to borrow.
- Enter the bank’s annual interest rate (the nominal rate, not the APR with fees).
- Enter the loan term and choose years or months.
- Pick your currency – the loan calculator remembers it next time.
- Read your monthly payment, total interest and the repayment schedule. Change any number and the results update instantly.
Loan EMI formula
A fixed-rate loan is repaid in equal monthly instalments. Each payment first covers that month’s interest; the rest reduces the balance. The equal monthly payment is:
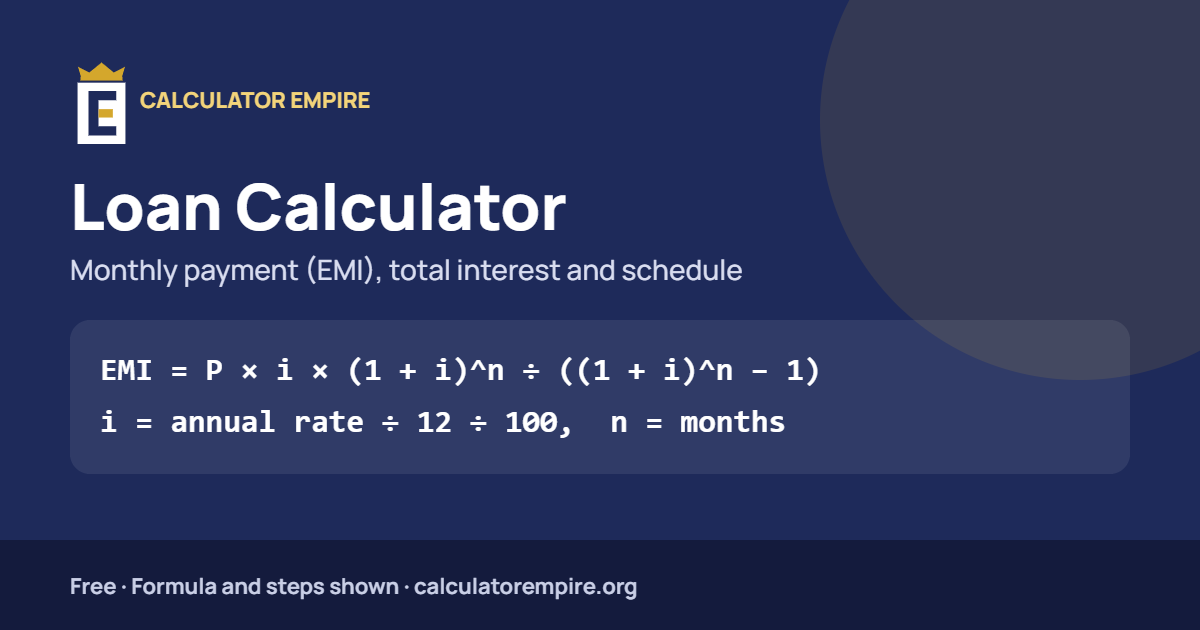
EMI = P × i × (1 + i)n ÷ ((1 + i)n − 1)
- P = loan amount (principal)
- i = monthly interest rate = annual rate ÷ 12 ÷ 100
- n = number of monthly payments
If the interest rate is zero, the formula simplifies to EMI = P ÷ n.
Loan calculator worked example
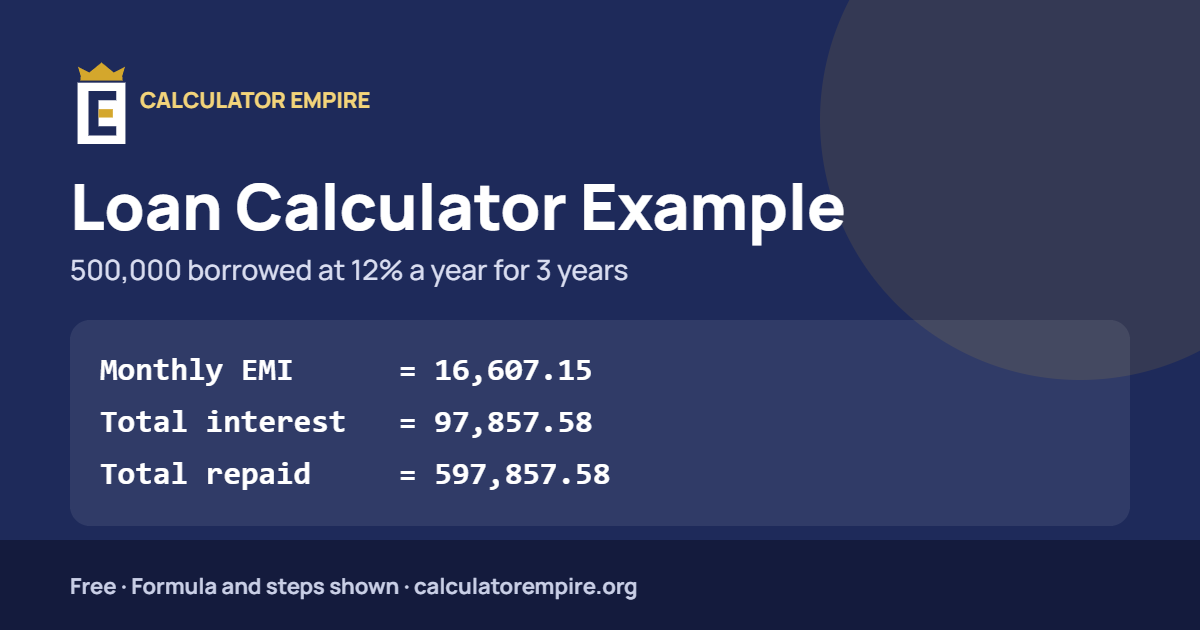
You borrow 500,000 at 12% a year for 3 years.
- Monthly rate i = 12 ÷ 12 ÷ 100 = 0.01
- Payments n = 3 × 12 = 36
- (1.01)36 ≈ 1.43077
- EMI = 500,000 × 0.01 × 1.43077 ÷ 0.43077 ≈ 16,607.15
- Total paid = 16,607.15 × 36 ≈ 597,857.58, so total interest ≈ 97,857.58
Enter the same numbers in the calculator above and you will get the same result, plus a year-by-year table showing how the balance falls.
How loan amortization works
In the first month of this example, interest is 1% of 500,000 = 5,000, so only 11,607.15 of the first payment reduces the balance. As the balance shrinks, the interest part of each payment falls and the principal part grows. By the final year most of each payment goes to principal.
| Year | Principal paid | Interest paid | Balance left |
|---|---|---|---|
| 1 | 147,207.78 | 52,078.08 | 352,792.22 |
| 2 | 165,877.41 | 33,408.45 | 186,914.82 |
| 3 | 186,914.82 | 12,371.04 | 0 |
This is why paying a little extra early in a loan saves far more interest than paying extra near the end.
Loan term comparison
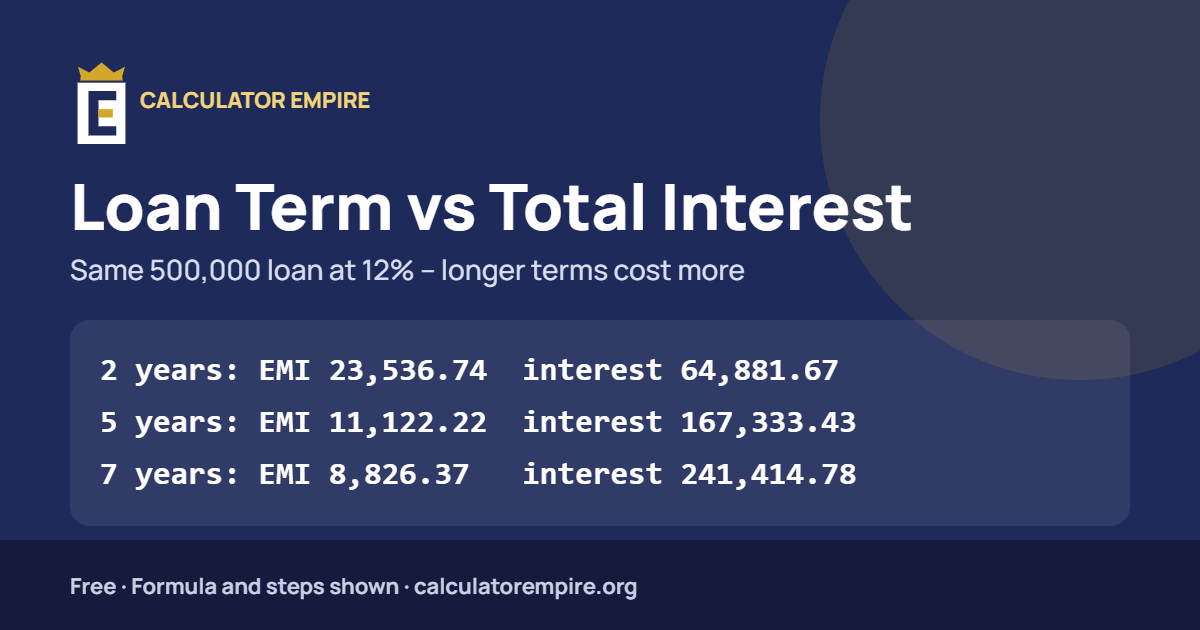
The same 500,000 loan at 12% costs very different amounts depending on how long you take to repay it:
| Term | Monthly EMI | Total interest |
|---|---|---|
| 2 years | 23,536.74 | 64,881.67 |
| 3 years | 16,607.15 | 97,857.58 |
| 5 years | 11,122.22 | 167,333.43 |
| 7 years | 8,826.37 | 241,414.78 |
What changes your monthly payment
| Change | Effect on EMI | Effect on total interest |
|---|---|---|
| Longer term | Lower | Higher |
| Shorter term | Higher | Lower |
| Higher interest rate | Higher | Higher |
| Larger down payment (smaller loan) | Lower | Lower |
Reducing balance vs flat interest rate
This loan calculator uses the reducing-balance method, where interest is charged only on what you still owe. Some lenders quote a flat rate, where interest is charged on the full original amount for the whole term. On 500,000 at 12% for 3 years, a flat rate means 180,000 of interest and an EMI of about 18,888.89 – roughly 82,000 more than the reducing-balance loan. Always ask which method a lender uses.
Fixed vs floating interest rates
The calculator assumes a fixed rate that stays the same for the whole term. Many home loans and business loans use a floating (variable) rate linked to a benchmark such as KIBOR in Pakistan or a central bank policy rate. When the benchmark rises, your EMI or term increases. To test the risk, run the calculator again with a rate 2–3% higher and check that the payment is still affordable.
Types of loans you can calculate
- Personal loans – usually 1 to 5 years, unsecured, higher rates.
- Car loans – 3 to 7 years; see the Auto Loan Calculator for tax and trade-in.
- Home loans – 10 to 30 years; see the Mortgage Calculator for tax and insurance.
- Education and business loans – any fixed-rate loan with equal monthly payments.
Tips before you take a loan
- Keep total monthly debt payments below about 30–40% of your take-home income.
- Compare the APR, not just the headline rate, because it includes processing fees.
- Ask about prepayment or early settlement charges before signing.
- Choose the shortest term whose EMI fits your budget comfortably.
- Check how a 1% rate difference changes the total interest using this loan calculator.
Tip: the early payments are mostly interest. Making an extra payment early in the loan cuts total interest the most. Check with your lender whether prepayment charges apply.
This calculator assumes a fixed rate, monthly payments and no fees. Real loans can add processing fees, insurance or taxes, so your lender’s figure may differ slightly.
Frequently asked questions
What is EMI?
EMI stands for Equated Monthly Instalment: the fixed amount you pay every month until the loan is repaid. Each EMI includes both interest and principal.
How is loan EMI calculated?
EMI = P × i × (1 + i)^n ÷ ((1 + i)^n − 1), where P is the loan amount, i is the monthly interest rate (annual rate ÷ 12 ÷ 100) and n is the number of monthly payments.
Does a longer loan term save money?
No. A longer term lowers each monthly payment, but you pay interest for more months, so the total interest is higher.
Is the interest rate the same as APR?
Not always. APR includes fees spread over the loan. Enter the nominal annual rate in the loan calculator to get the instalment, and use the APR to compare lenders.
How much loan can I afford?
A common guideline is to keep all monthly debt payments under 30–40% of your take-home income. Try different loan amounts in the calculator until the EMI fits that limit.
Does prepaying a loan reduce EMI or tenure?
It depends on the lender. Most banks reduce the remaining term and keep the EMI the same, which saves the most interest; some let you reduce the EMI instead.
Why is most of my early payment going to interest?
Interest is charged on the outstanding balance, which is largest at the start. As the balance falls, more of each payment goes to principal.
What is a flat interest rate?
A flat rate charges interest on the original loan amount for the whole term, so the real cost is much higher than the same reducing-balance rate. This loan calculator uses the reducing-balance method used by most banks.
Can I use this for a home or car loan?
Yes, for any fixed-rate loan with monthly payments. For homes with taxes and insurance use the Mortgage Calculator; for cars with trade-in and sales tax use the Auto Loan Calculator.
Is my loan calculation saved anywhere?
No. The loan calculator runs in your browser and the numbers you enter are not sent to our servers.
Sources
Related calculators
- Mortgage Calculator
- Auto Loan Calculator
- Compound Interest Calculator
- Simple Interest Calculator
- Savings Goal Calculator
- All Finance Calculators
Spotted an error? Tell us and we will check it.